Investor mortgage demand falls as refinancing takes over the loan market
New mortgage lodgements have fallen sharply since January as borrowers focus on refinancing. Investor demand is weakening fastest, although a greater share of remaining investment lending is flowing to newly built homes.
RentBuy Team
4 min read
Refinancing has overtaken new borrowing across a large mortgage broker network as higher interest rates, falling property prices and changes to housing taxes reshape Australia’s home loan market.
Refinancing represented a record 57 per cent of Loan Market Group’s mortgage lodgements in the final two weeks of September, according to its October market report covered by Australian Broker on Wednesday.
The headline reflects borrowers searching for a more competitive rate or loan structure rather than a surge in property purchases. After refinancing was removed and the figures were seasonally adjusted, the value of new mortgage lodgements was 24 per cent lower than at the end of January.
That comparison begins immediately before the Reserve Bank started lifting rates in February and before the federal budget changed the future tax treatment of residential property investment.
Investor lodgements recorded the largest retreat. Their value was down 45 per cent from the end of January and 23 per cent from the end of June, Loan Market Group found.
Total lodgements, including refinancing, increased by 10 per cent in September from their July low. The broker group nevertheless said the underlying market had not recovered because the improvement was being driven by existing borrowers moving loans rather than buyers funding additional property transactions.
Why the figures differ from settled-loan data
Loan Market Group’s figures track activity passing through its broker network, while Australian Bureau of Statistics lending data measures loans that have progressed further through the finance process. The time periods and measures are therefore different, but both point to a broad decline in investment activity.
PropTrack’s 2026 investor report, prepared with landlord insurer Terri Scheer, found the number of investor loans fell 9 per cent in the June quarter. Owner-occupier loans declined by a smaller 3 per cent over the same period.
The PropTrack report said interest rate rises began cooling investor demand before the May federal budget accelerated the slowdown. The budget changes limit negative gearing for future purchases of established residential property and change the capital gains tax treatment of certain investments.
Existing arrangements are grandfathered, while eligible newly built housing retains tax advantages. The changes are scheduled to apply to relevant future purchases from July 1, 2027.
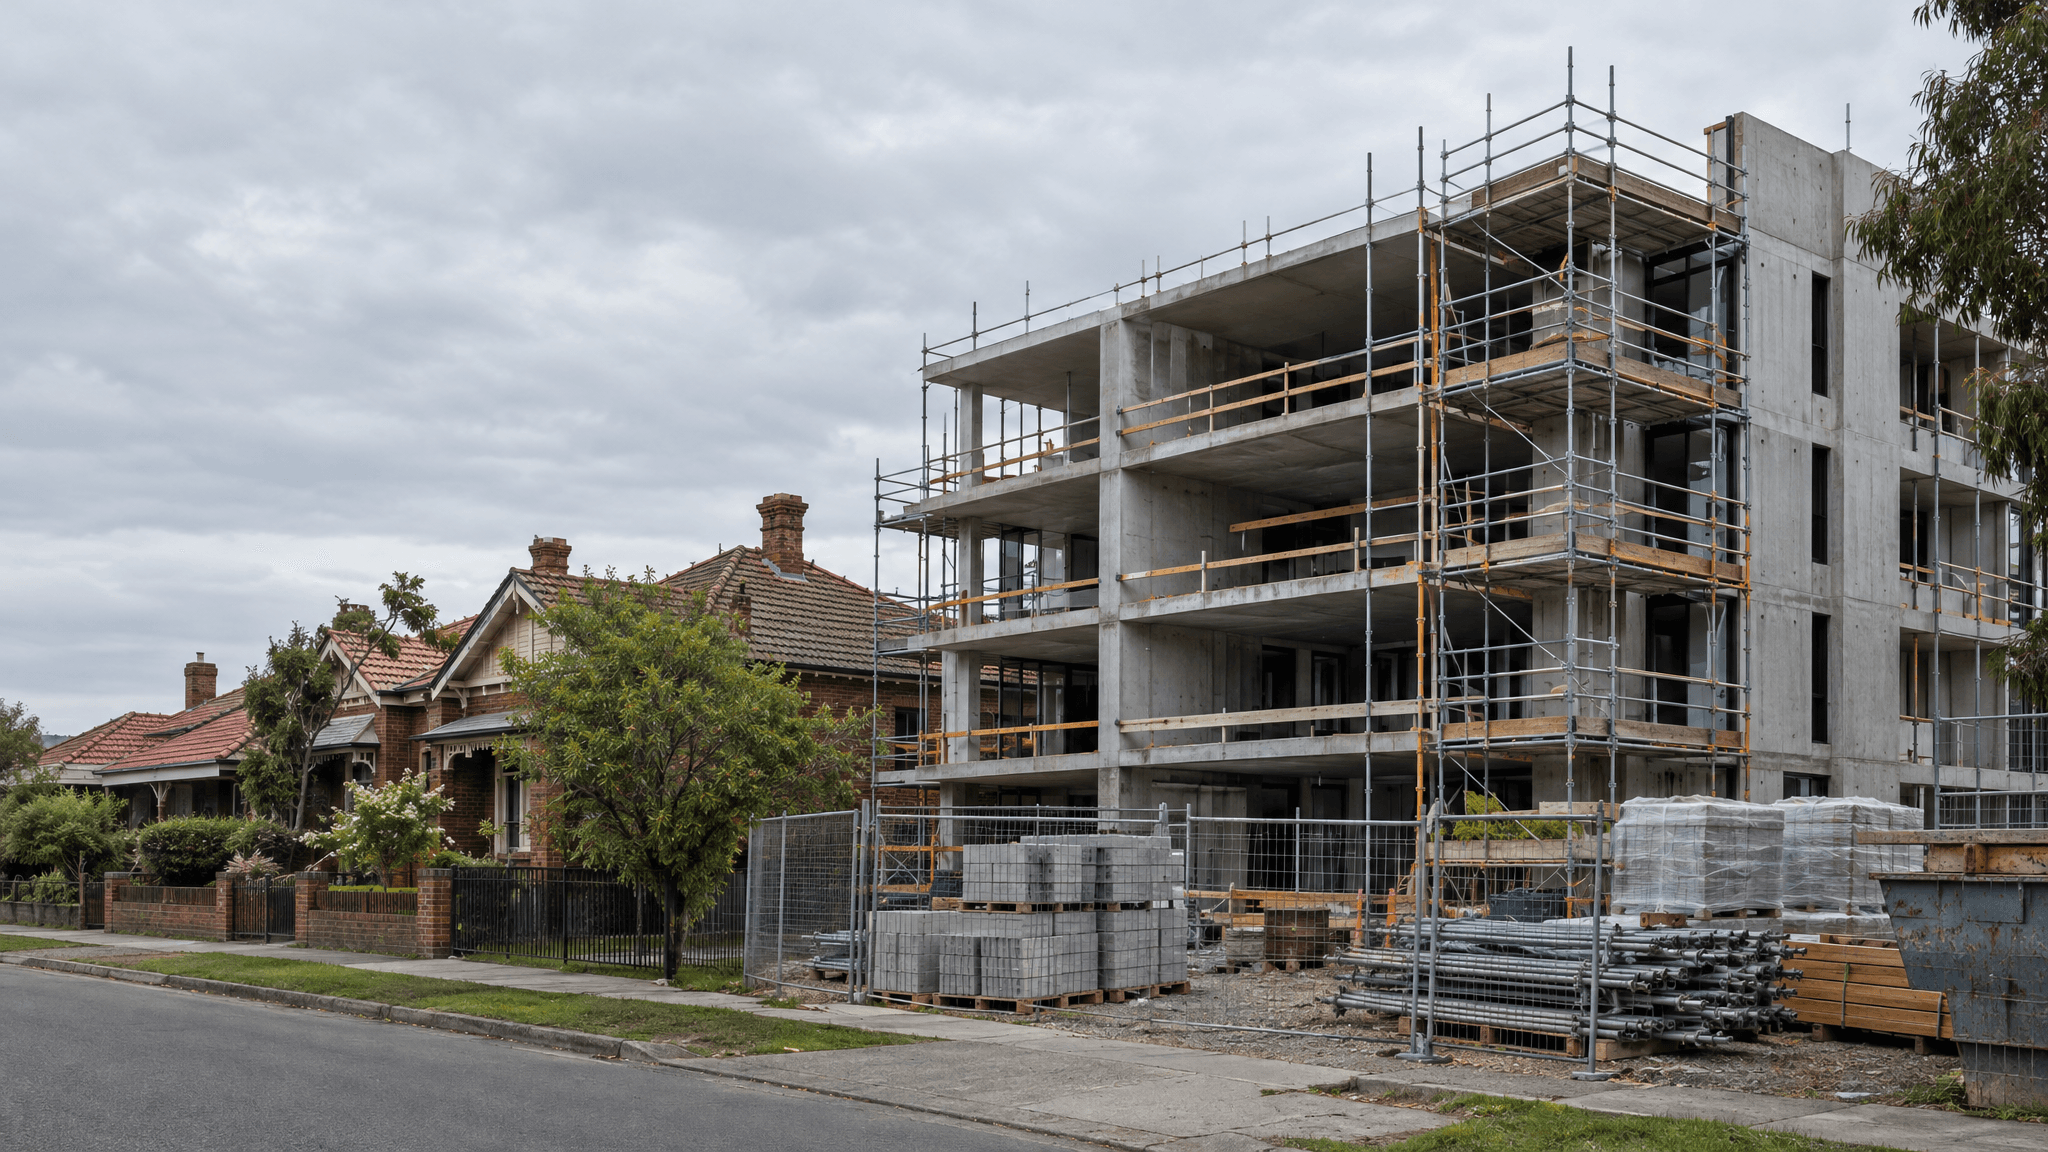
That distinction appears to be changing what some investors buy. PropTrack found that although overall investor loan numbers fell during the June quarter, loans used to build or buy new homes rose by 24 per cent.
This does not mean every investor is moving into a new apartment or house-and-land package. New developments carry their own risks, including construction delays, settlement valuations, builder problems, body corporate costs and uncertainty about the volume of similar dwellings completing nearby.
However, the lending shift suggests tax treatment is beginning to influence the balance between established and new housing before the reforms formally start.
Competition may ease unevenly
A retreat by investors can reduce competition for established homes, particularly lower-priced properties that appeal to both investors and first-home buyers. But the benefit for owner-occupiers is being limited by higher mortgage rates, which have reduced how much many households can borrow.
The effect on renters is also more complicated than the number of investor loans alone suggests. An investment property sold to another landlord remains in the rental pool, while one sold to an owner-occupier may leave it. At the same time, the owner-occupier could be leaving a rental home elsewhere.
Over the longer term, additional investment in genuinely new dwellings can expand total housing supply. Whether the current increase in new-home lending is large and sustained enough to offset the broader investor retreat remains uncertain.
For sellers, the type of likely buyer matters. An established apartment or house marketed primarily on its investment return may face a smaller audience, while properties attractive to owner-occupiers could prove more resilient. Accurate rental records, outgoings, strata information and realistic price expectations will become increasingly important.
What it means for you
- Existing borrowers should compare the interest rate, fees, features and total cost before refinancing, not just the advertised repayment.
- Buyers may encounter less investor competition for some established homes, but borrowing capacity remains constrained.
- Investors considering new property should assess construction, settlement and local supply risks as well as tax treatment.
- Sellers of investor-oriented properties should provide clear information on rent, expenses and condition and price for today’s finance environment.