Home buyers turn to partners, family and housemates as affordability pressure builds
New research suggests more prospective buyers intend to act within six months, but joint purchases, family gifts and income from spare rooms are becoming central to their plans.
RentBuy Team
5 min read
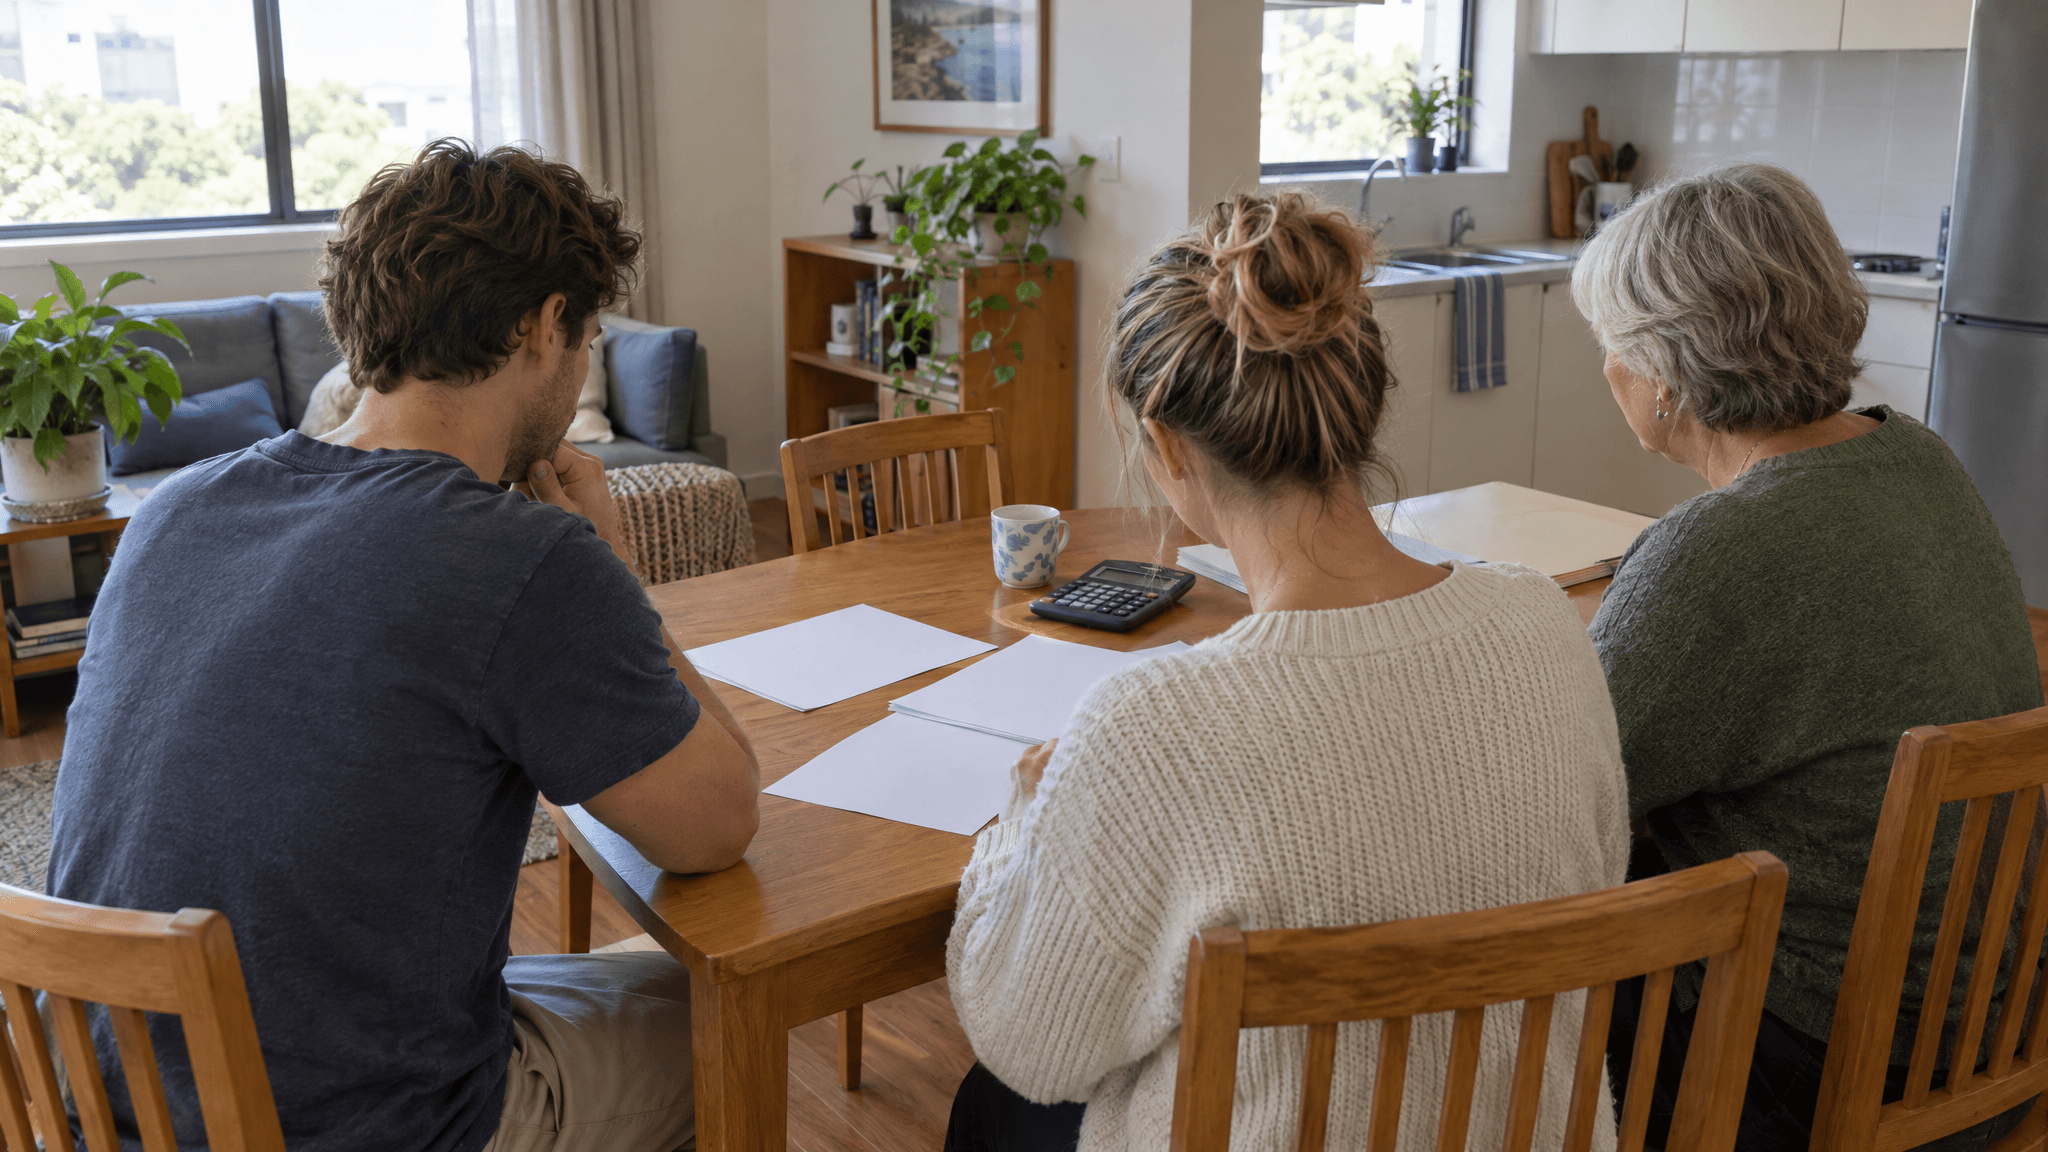
Prospective home buyers are bringing forward their plans despite higher interest rates, but many expect to share the financial load with partners, family members or future housemates.
Mortgage Choice’s latest Home Loan Report found 33 per cent of prospective buyers intended to purchase within six months, up from 19 per cent when the survey was conducted six months earlier. The result comes even as nearly half said interest rates had reduced their confidence about buying.
The twice-yearly report combines applications submitted through the Mortgage Choice broker network with an October survey of 1,000 Australians conducted by Honeycomb Strategy. It measures intentions rather than completed purchases, so the increase does not mean all those buyers will secure finance or find a suitable property.
It nevertheless shows how households are adjusting their plans as prices fall but borrowing remains difficult. Respondents were divided on the outlook: 35 per cent expected property prices to decline over the next six months, 32 per cent expected an increase and 29 per cent anticipated little change.
First home buyers are changing their approach
Among first home buyers, 23 per cent intended to purchase within six months. Their most commonly identified motivation was to stop paying rent, nominated by half of respondents, while 43 per cent wanted to avoid uncertainty such as rent increases or being required to move.
Almost half of first home buyers said they planned to purchase with a partner. Mortgage Choice reported this share had risen substantially since its April survey.
Deposit strategies were also becoming more dependent on family support. Twelve per cent expected a cash gift from relatives to contribute to their deposit, while only one in 10 said they had made no spending sacrifices while saving.
The figures illustrate an important distinction in the current market. Lower prices can reduce the amount needed to buy, but higher mortgage rates can simultaneously reduce the amount a lender is prepared to advance. A buyer may therefore find a cheaper property without gaining much additional choice.
Sharing a mortgage carries lasting obligations
Buying with another person can combine incomes and savings, but it also creates responsibilities extending well beyond settlement.
Moneysmart advises co-buyers to agree on ownership, costs and future decision-making before purchasing. A legal agreement can address issues such as each person’s contribution, responsibility for repairs and what happens if one owner wants to sell.
Co-borrowers generally remain responsible for the whole debt if the other borrower stops paying, not merely their assumed half. Couples, relatives or friends should therefore consider how repayments would be managed after unemployment, illness, separation or a decision to move elsewhere.
Family guarantees carry different risks. A guarantor may have to repay the amount covered by the guarantee if the borrower defaults, and an asset used as security could be at risk. Moneysmart recommends that guarantors understand the contract and obtain independent advice before signing.
Spare rooms are entering buyers’ budgets
One-third of prospective buyers surveyed planned to live with family, housemates or boarders who would contribute to household costs. Of those arrangements, 61 per cent involved multigenerational living with parents or adult children.
That income should not automatically be treated as guaranteed mortgage capacity. A room can remain vacant, household relationships can change and lenders may apply their own rules when assessing proposed rent or board.
There can also be tax consequences. The Australian Taxation Office says rent received from letting part of a home generally needs to be declared, and using part of a main residence to earn assessable income may affect the capital gains tax treatment when it is sold. Domestic board or lodging arrangements can be treated differently, making professional advice useful before relying on the income.
Falling prices are changing buyer calculations, but the survey suggests sharing costs is becoming the price of entry for many households.
The report also found the average value of loan applications through Mortgage Choice had risen 6.8 per cent over the year to $690,246. Western Australia recorded the largest increase, followed by South Australia and the Northern Territory, and Queensland.
For buyers, the practical test remains whether a purchase can be sustained without every part of the plan going perfectly. Proposed contributions from relatives or housemates should be documented and stress-tested alongside rates, insurance, strata charges, maintenance and other ownership costs.
What it means for you
- Get finance assessed before treating falling prices as an increase in buying power.
- If buying jointly, document ownership, repayments and an exit plan before exchanging contracts.
- Family guarantors should obtain independent legal and financial advice.
- Check the tax implications before relying on rent from a spare room.